
Key takeaways
- Business credit cards don't trigger Chase's 5/24 rule, letting you earn bonuses without losing access to personal Chase cards.
- The Ink Business Preferred delivers $2,050 in welcome value and Sapphire Reserve for Business provides $300 annual travel credit, both integrating directly with personal Chase portfolios.
- American Express business cards unlock access to 20 airline and hotel transfer partners, while Citi/AAdvantage offers Oneworld alliance perks.
- Applying for business cards between personal applications extends your earning timeline without consuming slots that count toward the 5/24 rule.
Chase’s credit card portfolio includes some of the industry’s most valuable welcome bonuses and earning structures, but the bank enforces strict application policies. The most significant barrier is the 5/24 rule, an undisclosed but widely confirmed guideline: applicants who have opened five or more credit accounts across any issuer within the preceding 24 months face near-certain denial for new Chase cards. All personal credit card accounts count toward this threshold, including those without preset spending limits and certain store cards.
However, a large category of credit products exists outside this calculation: business credit cards. Most business cards issued by Chase and other major issuers don’t report to personal credit bureaus and therefore don’t affect your 5/24 standing. This creates a legitimate pathway to earn welcome bonuses and accumulate points without consuming your finite allocation of Chase personal card slots.
How Business Cards Stay Below the Radar
The reason business cards bypass 5/24 restrictions stems from credit reporting practices. Most business card issuers, including Chase, maintain separate business credit infrastructure that doesn’t merge with the personal credit bureaus—Equifax, Experian, TransUnion—where the 5/24 rule operates. As long as your business card account remains in good standing, the account activity stays invisible to personal credit scoring.
This distinction means you can hold a business card from Chase while maintaining eligibility for a personal Chase card application, provided all other approval criteria are met. The business card doesn’t consume one of your five slots.
That said, not all business cards follow this pattern. Most Capital One business cards do report to personal bureaus, though three exceptions exist: Capital One Venture Business, Capital One Venture X Business, and Capital One Spark Cash Plus. Knowing which cards stay off your personal credit file is essential before applying.
Six Business Cards Worth Your Attention
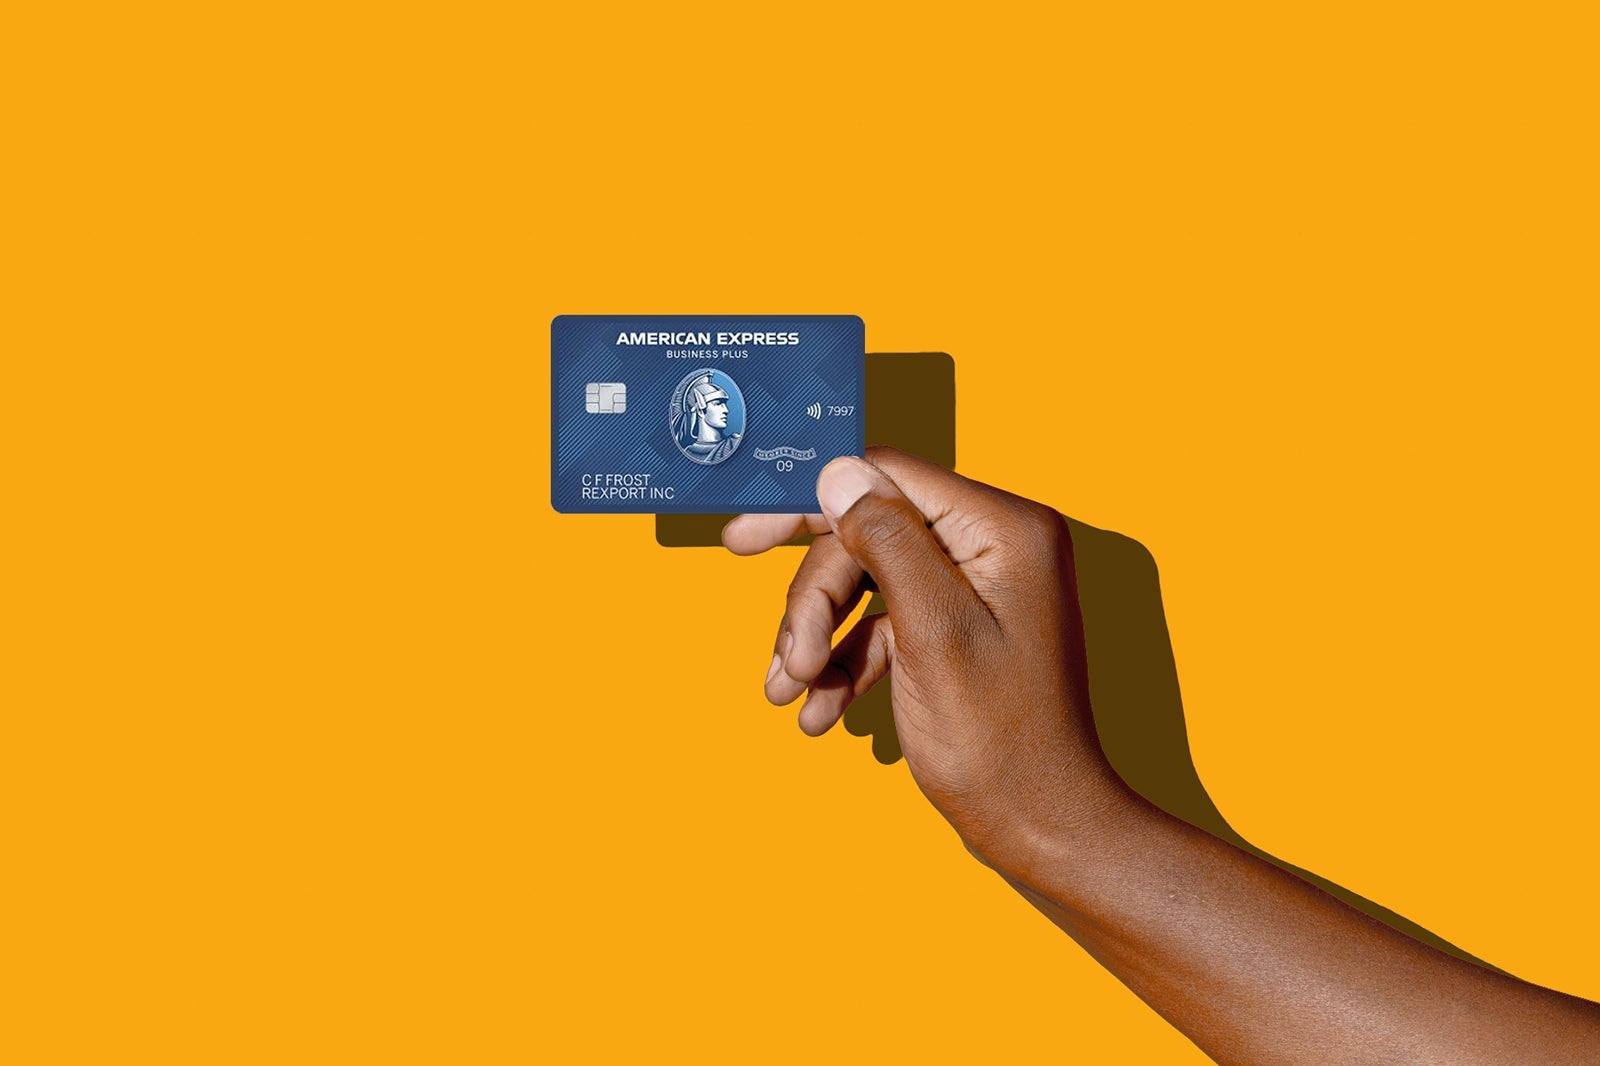
American Express Blue Business Plus
This Amex card caters to small businesses with modest annual spending. The welcome offer delivers 15,000 bonus points after $3,000 in purchases within the first three months, valued at $300 according to TPG’s August 2026 valuations. The card earns 2 points per dollar on all purchases for the first $50,000 in annual spending, then 1 point per dollar thereafter. That structure rewards businesses that stay under the $50,000 threshold without penalty.
You’ll also gain access to American Express’s roster of 20 hotel and airline transfer partners, converting Membership Rewards points into premium cabin tickets or luxury hotel stays.
Chase Ink Business Unlimited
The Ink Business Unlimited takes a different approach: unlimited cash back rather than transferable points. The welcome bonus provides $1,000 cash back after $8,000 in spending during the first four months. The card earns an uncomplicated 1.5% cash back on every business purchase with no bonus categories to track.
Its real power emerges when paired with personal Chase cards. If you hold the Chase Sapphire Preferred, you can transfer that card’s Ultimate Rewards points to Chase’s 14 airline and hotel partners, then combine them with cash back earned on the Ink Business Unlimited. The card carries no annual fee, making it a low-friction way to stay under 5/24.
Citi / AAdvantage Business World Elite Mastercard
This card targets frequent American Airlines fliers or Oneworld alliance members. The welcome bonus awards 65,000 AAdvantage miles after $4,000 in spending within the first four months, valued at $910 in August 2026. An introductory year includes no annual fee; thereafter, the fee is $99.
Cardmembers receive a free checked bag on domestic flights for the cardholder and up to four travel companions on the same reservation, 25% off inflight Wi-Fi and food or beverage purchases, and the ability to earn a companion certificate ($99 plus taxes and fees) by renewing the card and spending $30,000 or more in a cardholder year.
Chase Ink Business Preferred
The Ink Business Preferred offers one of this selection’s highest welcome bonuses: 100,000 Ultimate Rewards points after $8,000 in spending during the first three months, worth $2,050. Despite qualifying for the 5/24 rule during approval, the card itself doesn’t count toward your standing once opened.
The card earns Ultimate Rewards in multiple bonus categories relevant to business operations and can transfer points to Chase’s 14 hotel and airline partners. It also includes primary car rental insurance and cellphone protection, perks that business travelers frequently use.
Marriott Bonvoy Business American Express
Marriott loyalists can leverage this Amex card’s substantial welcome offer: up to 125,000 Bonvoy points (75,000 after $6,000 in six months, plus 50,000 after an additional $3,000, totaling $9,000 in spending within six months), valued at up to $938.
The card includes complimentary Marriott Gold Elite status, which provides 25% bonus points on Marriott stays and 2 p.m. late checkout subject to availability. Cardmembers receive a free night award annually following the renewal month. Given Marriott’s portfolio of over 10,000 properties worldwide, these benefits and free night awards translate to tangible value.
Chase Sapphire Reserve for Business
The premium option for business owners is the Sapphire Reserve for Business. The welcome bonus reaches 200,000 Ultimate Rewards points after $30,000 in spending during the first six months. Despite the $795 annual fee, the card provides $300 in annual travel credits and airport lounge access, offsetting the cost for business travelers.
Like the Ink Business Preferred, the Sapphire Reserve for Business requires being under 5/24 to qualify but doesn’t increase your count upon approval.
Strategic Application Timing Preserves Opportunities
The chief advantage of business cards is extending your earning window. Rather than opening five personal cards over 24 months and hitting the 5/24 wall, you can apply for a business card between personal applications to maintain momentum. Each business card opened doesn’t consume a personal slot, effectively allowing you to earn welcome bonuses on a staggered timeline.
Most people don’t operate a traditional business, yet remain eligible for business cards. Income from freelance work, reselling inventory, or services like dog walking or rideshare driving qualifies. Issuers rarely verify business legitimacy, though accuracy on your application is still essential.
Practical Considerations Before Applying
Business cards lack the same consumer protections as personal cards, so keep business and personal expenses strictly separate. Mixing expenses complicates taxes and may trigger account closure if the issuer objects to personal spending.
All point and mile valuations referenced in this article use TPG’s August 2026 benchmarks. Actual redemption value depends on your preferred use—a business traveler maximizing airline perks may extract more from an airline card, while someone who values simplicity may prefer flat-rate cash back.
Frequently Asked Questions
Do business credit cards count toward Chase's 5/24 rule?
No. Most business credit cards don't report to personal credit bureaus and don't count toward the 5/24 calculation, so opening a business card won't affect your eligibility for Chase personal cards.
What's the highest welcome bonus among these six business cards?
The Chase Sapphire Reserve for Business offers 200,000 bonus Ultimate Rewards points after $30,000 in spending during the first six months. Based on TPG's August 2026 valuations, this ranks highest among the cards reviewed.
Do I need a legitimate business to apply for these cards?
No. Income from freelance work, reselling, dog walking, or rideshare driving qualifies you to apply. Issuers rarely verify business legitimacy, though you should provide accurate information on your application.
